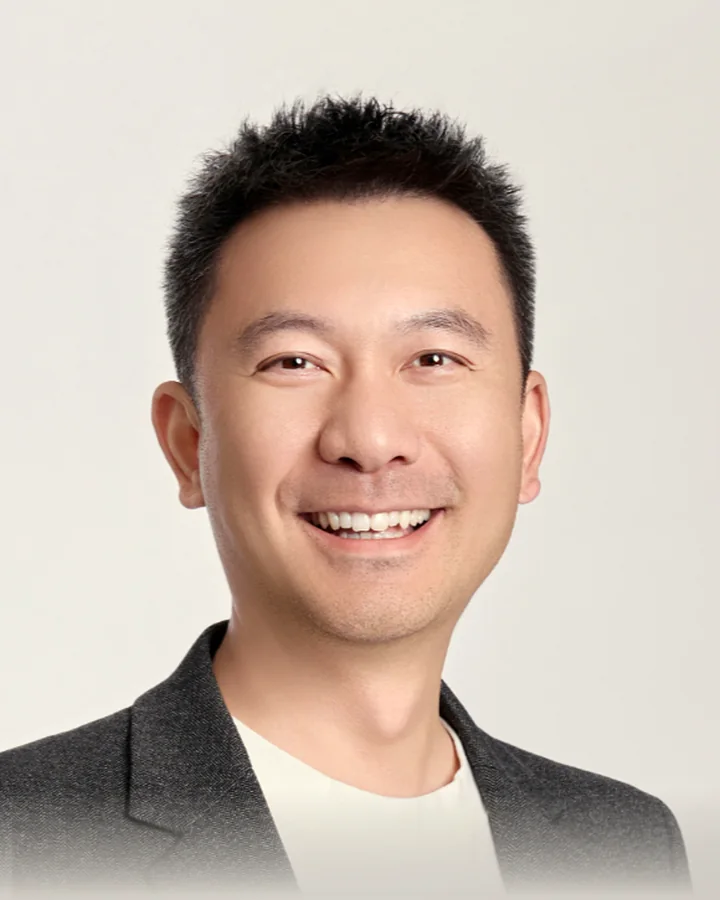
Austin Wang
- Focus
- Tax · Estate · Retirement
- Credentials
- CFP® · EA
- Languages
- 普通话 · English
Austin is a CERTIFIED FINANCIAL PLANNER™ professional and an Enrolled Agent (a tax practitioner licensed directly by the IRS to represent taxpayers), with more than 18 years in the financial industry.
He builds comprehensive plans for Chinese-American families and business owners. Typical questions include how to save into retirement accounts while working and in what order to draw them down in retirement; how a business owner can use a defined benefit or cash balance plan to save more and deduct more before retiring; and how a family’s assets pass to the next generation through wills, trusts and insurance. He starts by working out the family’s taxes and cash flow, and only then decides whether tools such as insurance, annuities or trusts are needed, and how much.
Alongside one-on-one planning, Austin teaches in public: he explains retirement, tax and legacy topics on his Chinese-language YouTube channel and on Xiaohongshu, has written more than fifty in-depth articles on austinwangfp.com, runs regular online seminars, and is the author of Rethinking Wealth in America. At Meta Mega Group he also speaks at the firm’s Tuesday seminars.
With money, it pays to see clearly, and early.
Questions to bring to Austin
- I am close to retiring: in what order should I draw from my 401(k), IRA and Roth accounts to keep total taxes lower?
- My business earns well: can I save more for retirement and pay less tax before I retire?
- Our assets are split between the U.S. and China: how should we plan for estate and gift taxes?
- Do we need a trust, and how do we choose between a will and a trust?
- Are annuities or life insurance right for our family, and how much is reasonable?
- Which financial decisions should come first before or after immigrating?
Related services
Retirement Planning →
The question we hear most is “how much can I spend each year once I retire?” The answer depends on which accounts your money sits in, when each one is tapped, and how much tax is due on the way out. Our CFP® professional models your 401(k), IRAs, Roth accounts, Social Security and rental income together to build a spending plan that holds up across different market conditions.
U.S.–China Tax Planning →
For families who have just immigrated or split time between countries, the most important date on the tax calendar is often the day they become U.S. tax residents, because from then on worldwide income is reported to the IRS. Our enrolled agent and partner CPAs prepare individual and business returns, and work out the tax consequences before decisions like immigrating, selling a home or a company, or receiving a gift from parents.
Trust & Legacy Planning →
In California, assets not held in a trust at death usually go through probate, a court-supervised process that is public, slow, and carries statutory attorney and executor fees based on the value of the estate. We work with partner attorneys to put living trusts and wills in place, and your planner brings estate tax, cross-border assets and each child’s circumstances into a single legacy plan.
Retirement Plans for Business Owners →
The question business owners ask most is whether, after a few profitable years, there is a way to put more pre-tax money toward retirement than a 401(k) allows. Under 2026 rules, one person can receive at most $72,000 in a 401(k) from employee and company contributions combined (catch-up contributions from age 50 are on top), and saving more usually means adding a DB Plan or Cash Balance Plan, where an actuary calculates the contribution. We help owners decide which combination fits, roughly how much to contribute each year and how to invest plan assets, and we coordinate setup and annual upkeep with partner third-party administrators (TPAs, outside firms that handle plan documents, employee testing and annual filings), actuaries and CPAs.
Integrated Family Plan →
Many families come to us already holding several separate arrangements: a policy, a trust, a few retirement accounts and an immigration timeline from their attorney, but nobody has looked at them together. An integrated family plan does exactly that: we map the family’s assets, income, status and goals, find where arrangements conflict or leave gaps, and set out each step in priority order.
Seminars
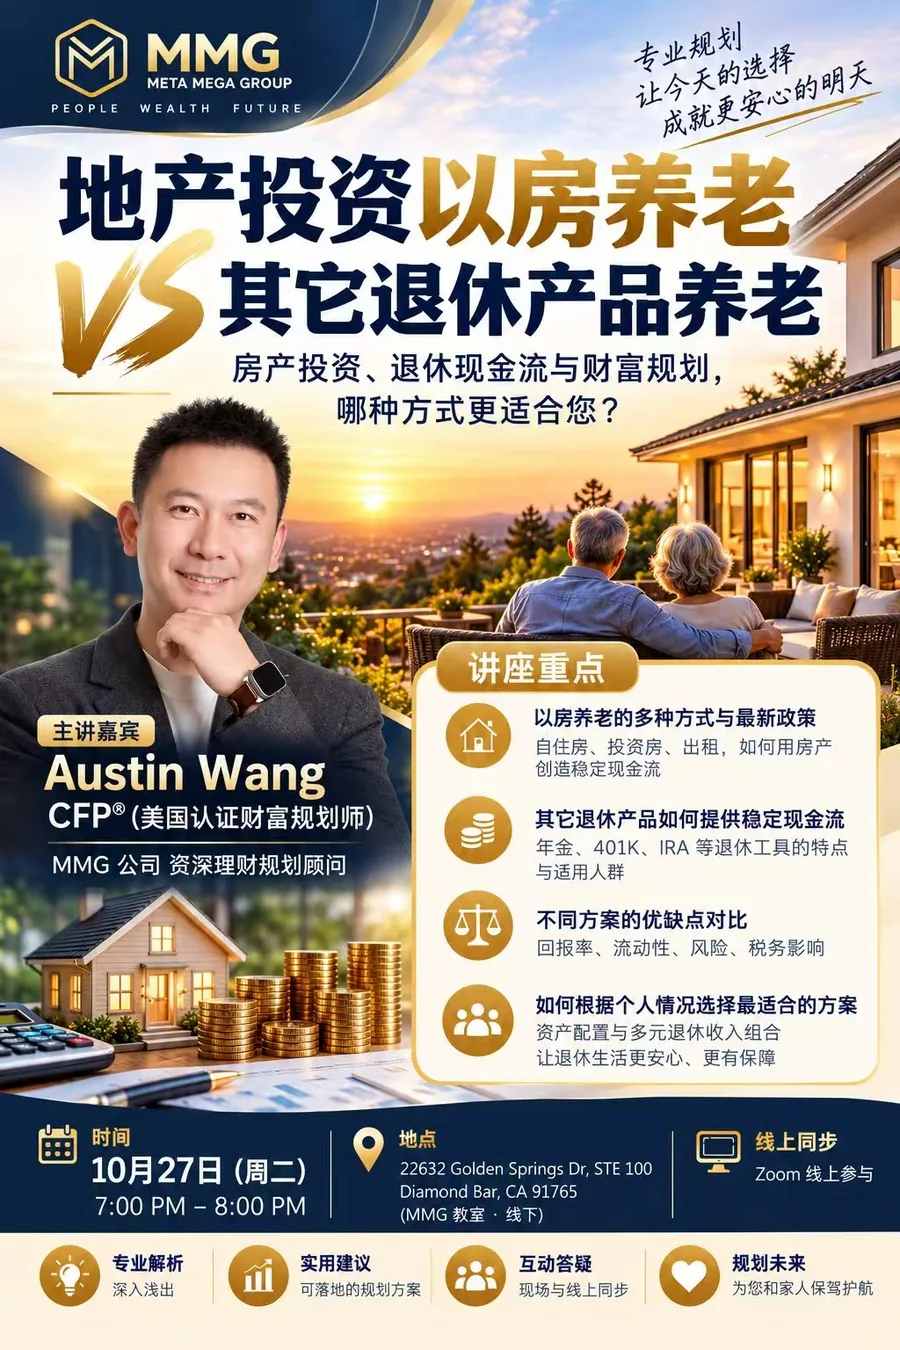 10.272026
Retiring on Real Estate vs. Other Retirement Products
SpeakerAustin Wang, CFP®, EA
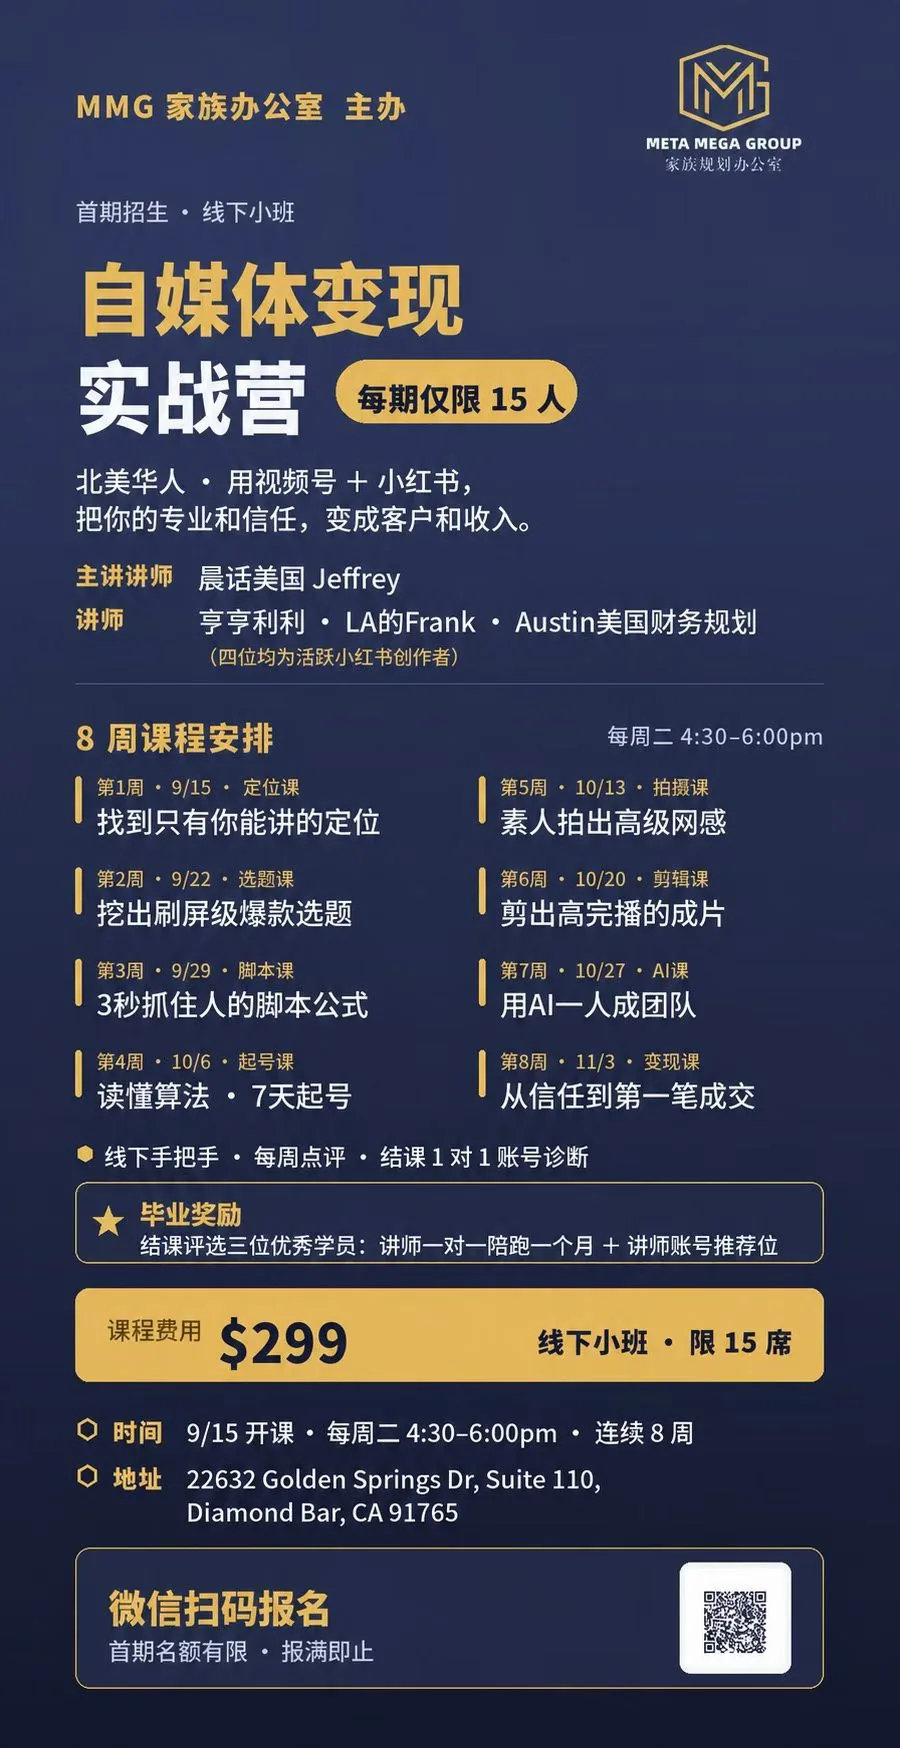 09.152026
Creator Bootcamp: Turning Expertise into Clients (First Cohort)
SpeakerJeffrey of 晨话美国 (lead); Henry, Frank, Austin Wang
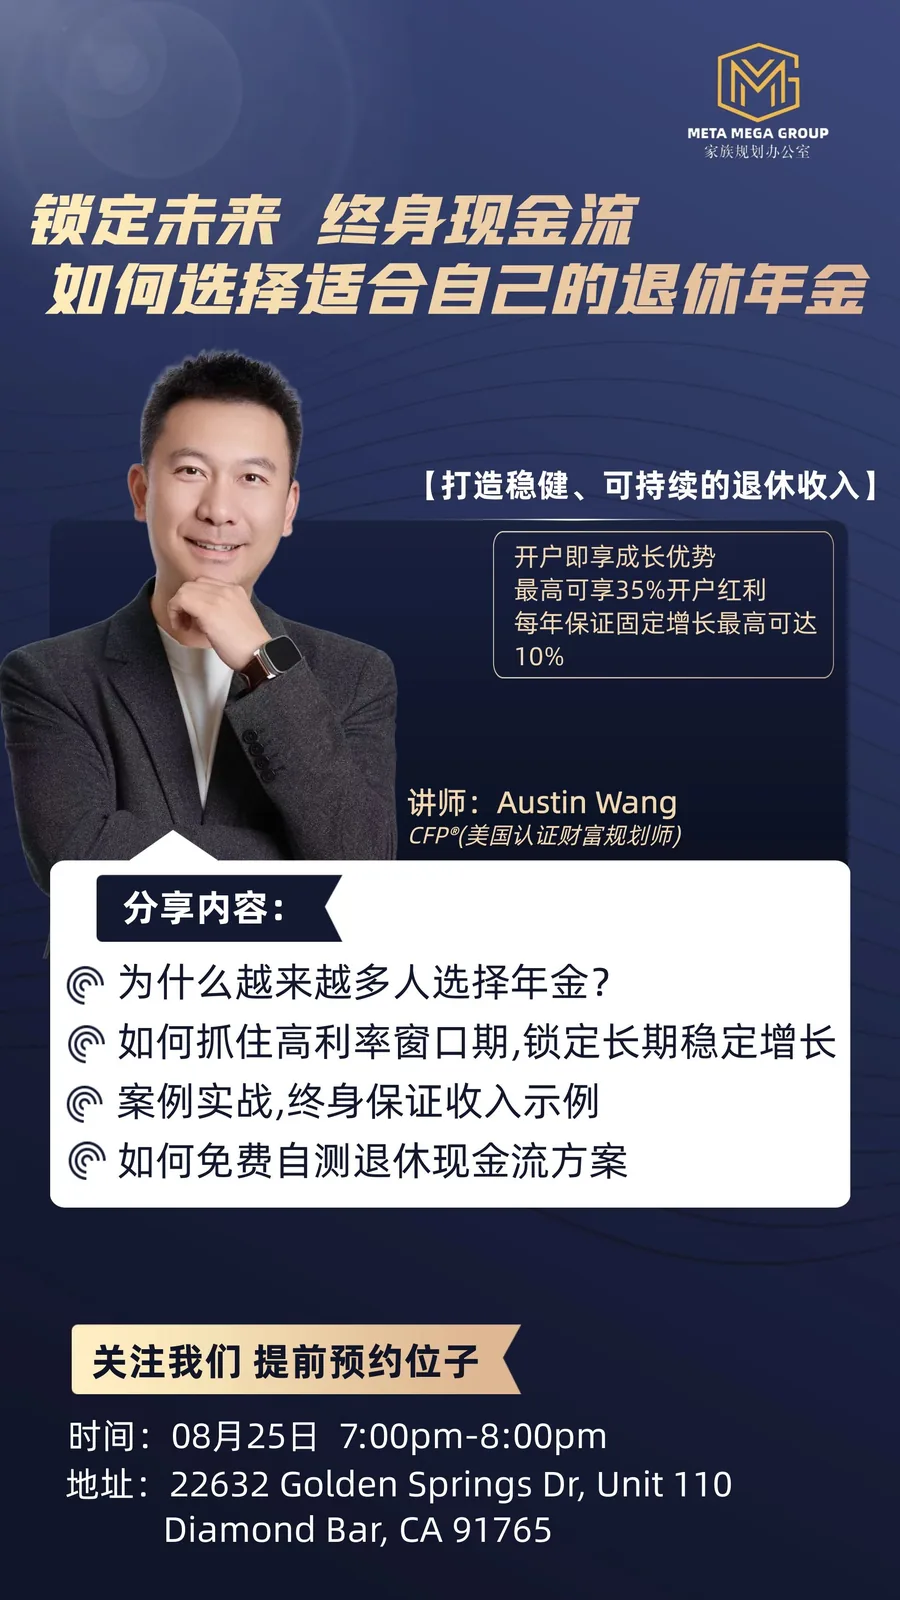 08.252026
Lifetime Income: How to Choose a Retirement Annuity
SpeakerAustin Wang, CFP®, EA
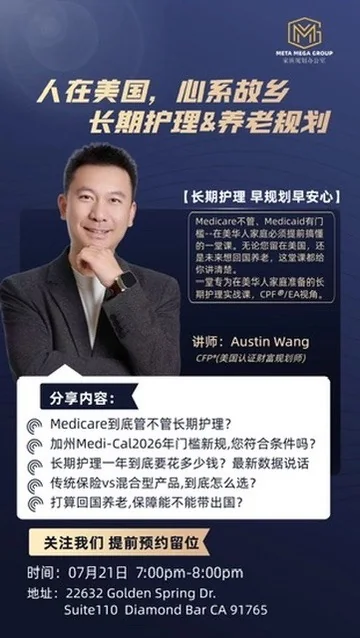 07.212026
Long-Term Care and Retirement Planning for Families Between Two Countries
SpeakerAustin Wang, CFP®, EA
More of the team
Jeffrey Chen
PartnerBusiness development · Media
Chris Li
PartnerPartnerships · U.S.–China business
Henry Han
PartnerLife & health insurance · Technology
Richard Wang
PartnerRetirement income · Insurance & annuities · Cross-border · Art & collectibles
Gigi Wang
PartnerEducation · Client service